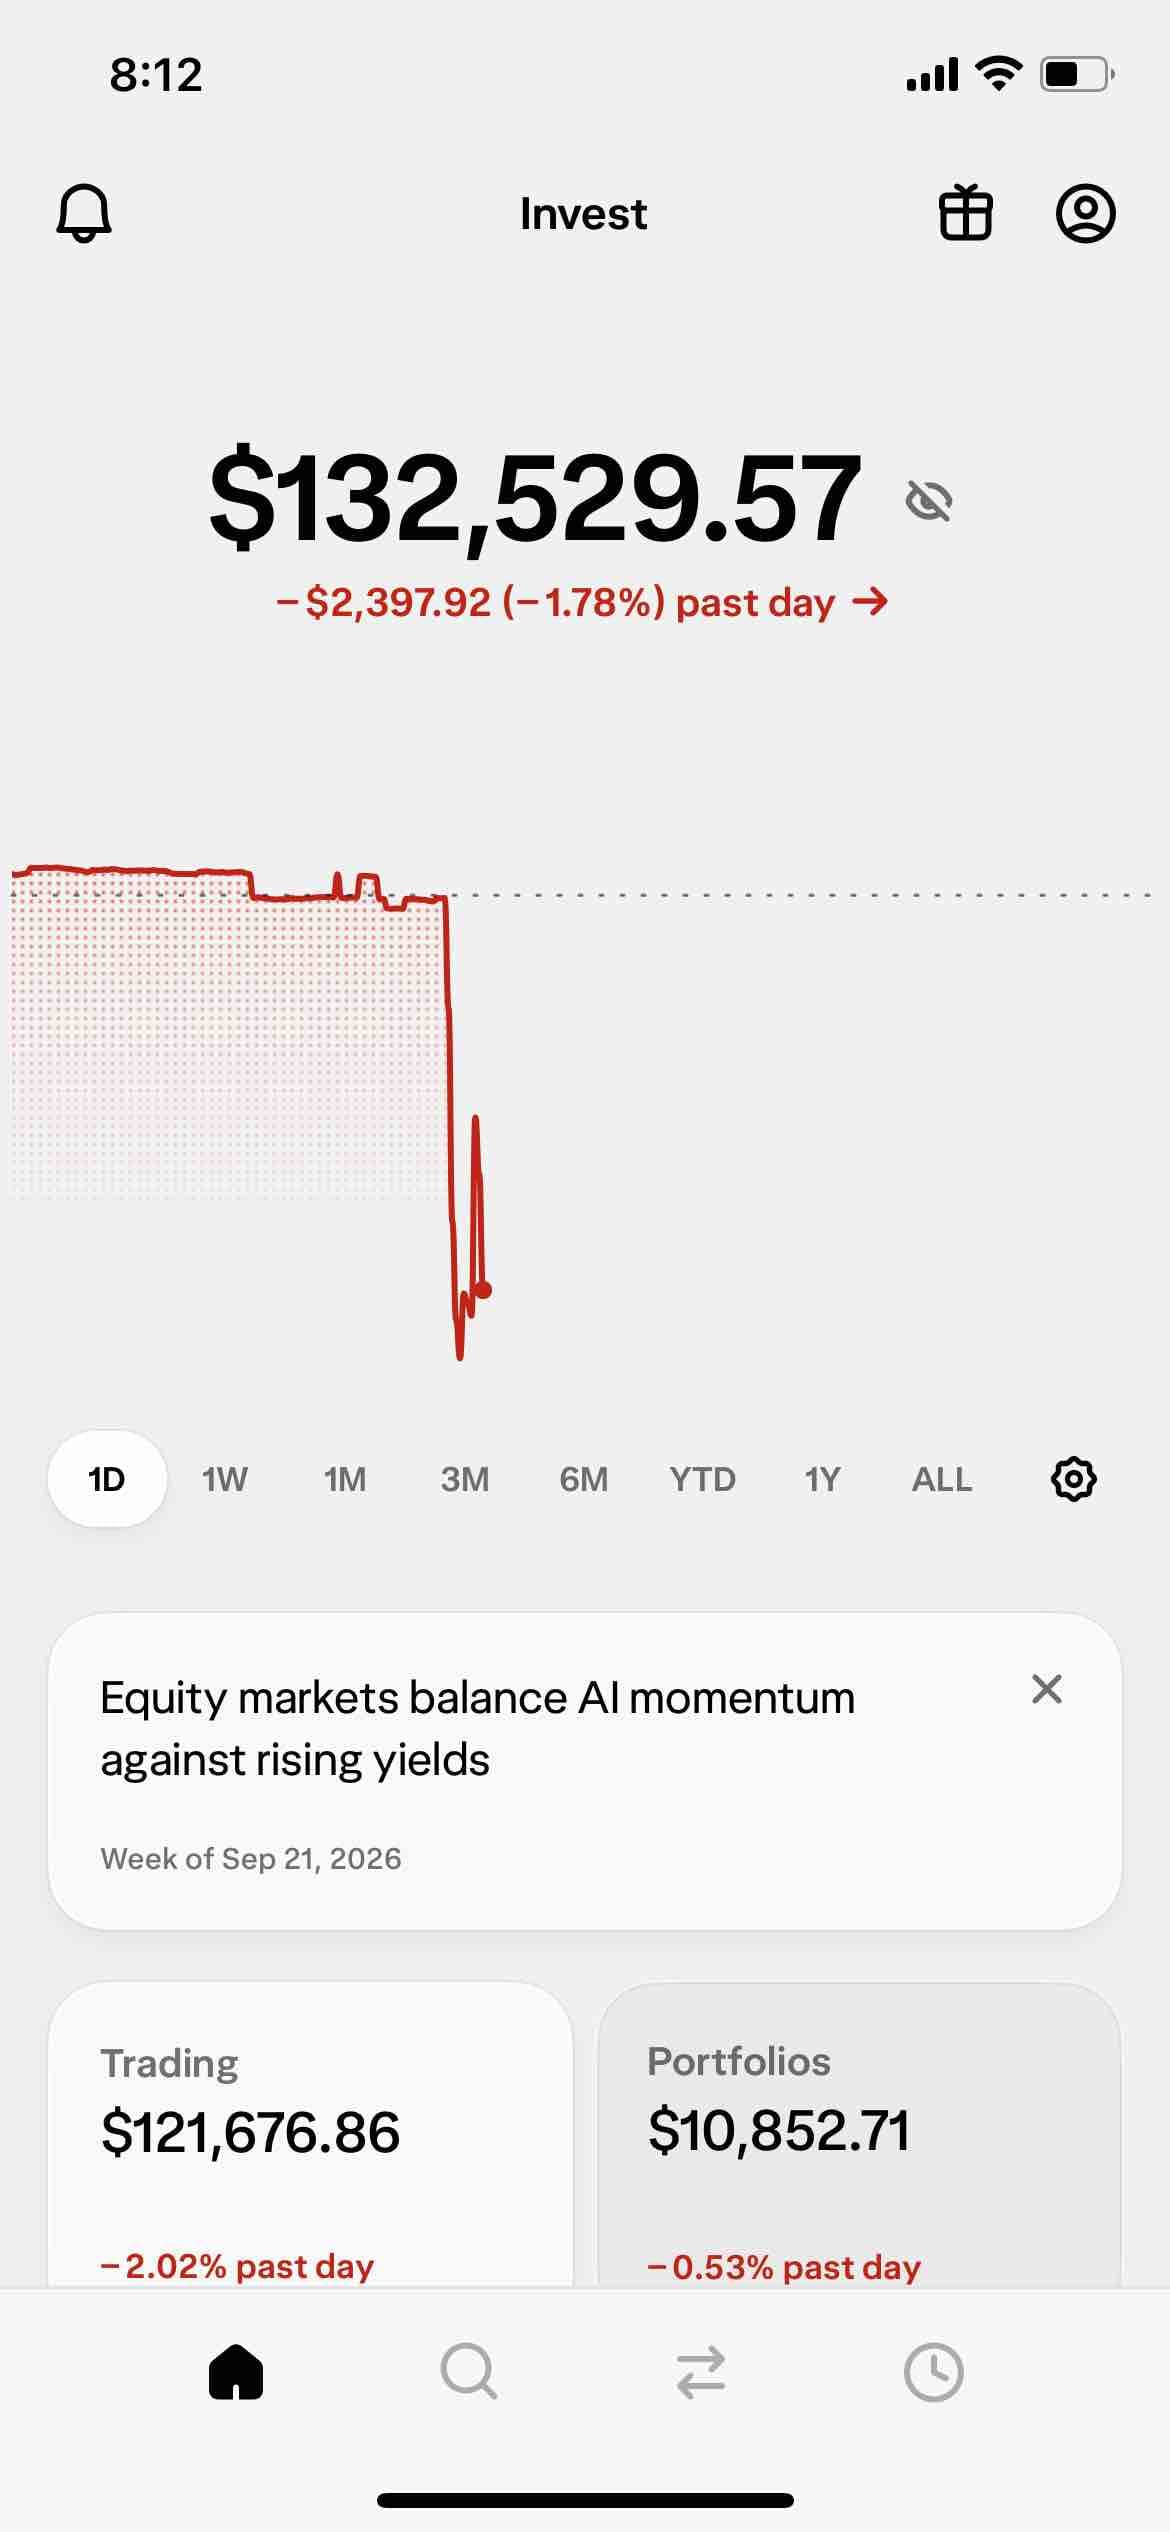
I think during the portfolio building phase i got too wrapped up in diversification rather than focus on funds that i have conviction in. $UTES and $PAYI were exactly that. I didnt know why i had them i just knew people said it was good to have. But after watching these both tank over the last few months, especially in this bond yield environment, i trimmed it and reallocated to funds i think will be more fruitful for this specific portfolios purpose of feeding my registered accounts.
My investing story has was supposed to just happen on a well-groomed, lit, easy highway, however, Just like life, I had to swerve or run over road kill, yell at my portfolio for not doing what I thought it should be (drivers), hit potholes, decided that the best and fastest route was this other alternate road, which was slow, long windy and brought me closer to my starting point then my destination. I had to pull over, take a nap, reassess what I was doing and start from scratch. With renewed focus and taking the time to understand what I was truly trying to achieve, I'm well on my way now with my goal to retire and spend my remaining time on this earth, choosing to do what I want to do. Kids, travel, volunteer, etc. In 2012, I was given good advice from a very wise investor; stick with Canadian banks, they are tried, tested and true. I was told to be boring and I would get there. I chose to go the other way, bought volatile positions that went bankrupt or to this day are pretty much worthless (these are my roadkill, potholes and terrible drivers - to be fair - we are all terrible drivers at least at some point, most don't want to self-assess. In 2016, I started over, refocus my strategy and bought the safe positions, banks and utilities, things were going somewhat ok but still to 'slow' for my goals so... In 2021, I pulled my entire portfolio, which was just over 100k and got into the rental business - still in this btw. I realized that while this is a good investment, there are a LOT of things I did not really comprehend until the bills started coming - a new deck, roof, property taxes, taxes, insurance, more taxes, and then more taxes. I haven't even talked about tenants, unpaid rent, etc. This is my 'the best and fastest route was this other alternate road, which was slow, long windy and brought me closer to my starting point then my destination' so... In 2022, still not happy with my investment growth, I did some research and decided to go with the CC ETF strategy. For me, I'm comfortable with this, I'll take the the return today instead of growth tomorrow. Not for everyone, I get it. Do your thing. This is my 'pull over, take a nap, reassess what I was doing and start from scratch.' My dividend returns: 2022 - $35.99 2023 - $458 2024 - $5,071 2025 - $17,564 2026 - $21,576 still have Oct, Nov and Dec so should push just north of $30,000 I don't plan on changing my strategy, I know there will be every driving scenario over there - I have no doubt at some point, I'll be calling a tow truck but I'm moving forward, I'll just need some help every now and again. I just crossed $3,200/mth in returns and a total portfolio of $240k. I'm reinvesting every dollar and at $10,000/mth, I'm shutting it down. Dec 2030 is my goal date. For me, the road less travelled is starting late but I tell people I speak with who aren't investing and want to, Day 1 is THE best day to start. There is is no 'too late'. read more
Added to my $SPXE , $HHLE , $CCHI , $MSTE , $SSHI positions using Sept distributions and some additional funds before tomorrows ex-div date This should increass my monthly income from CC-ETF’s by about 7-8%
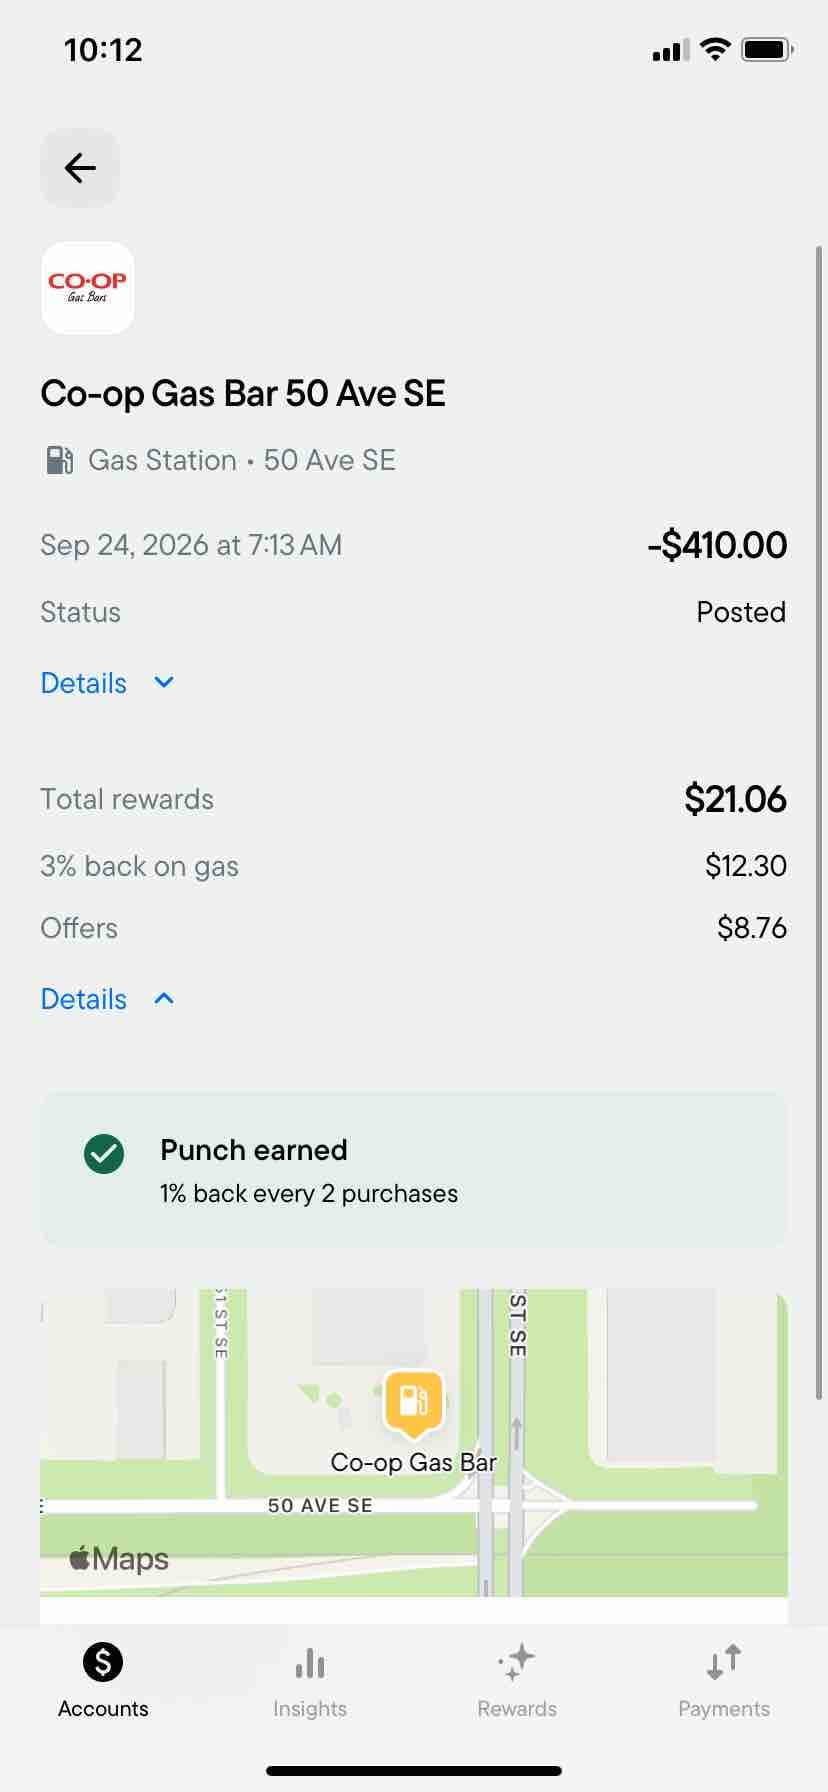
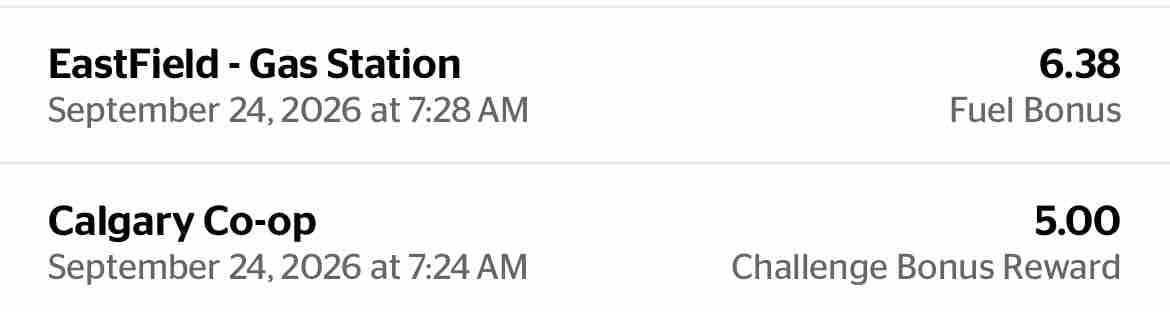
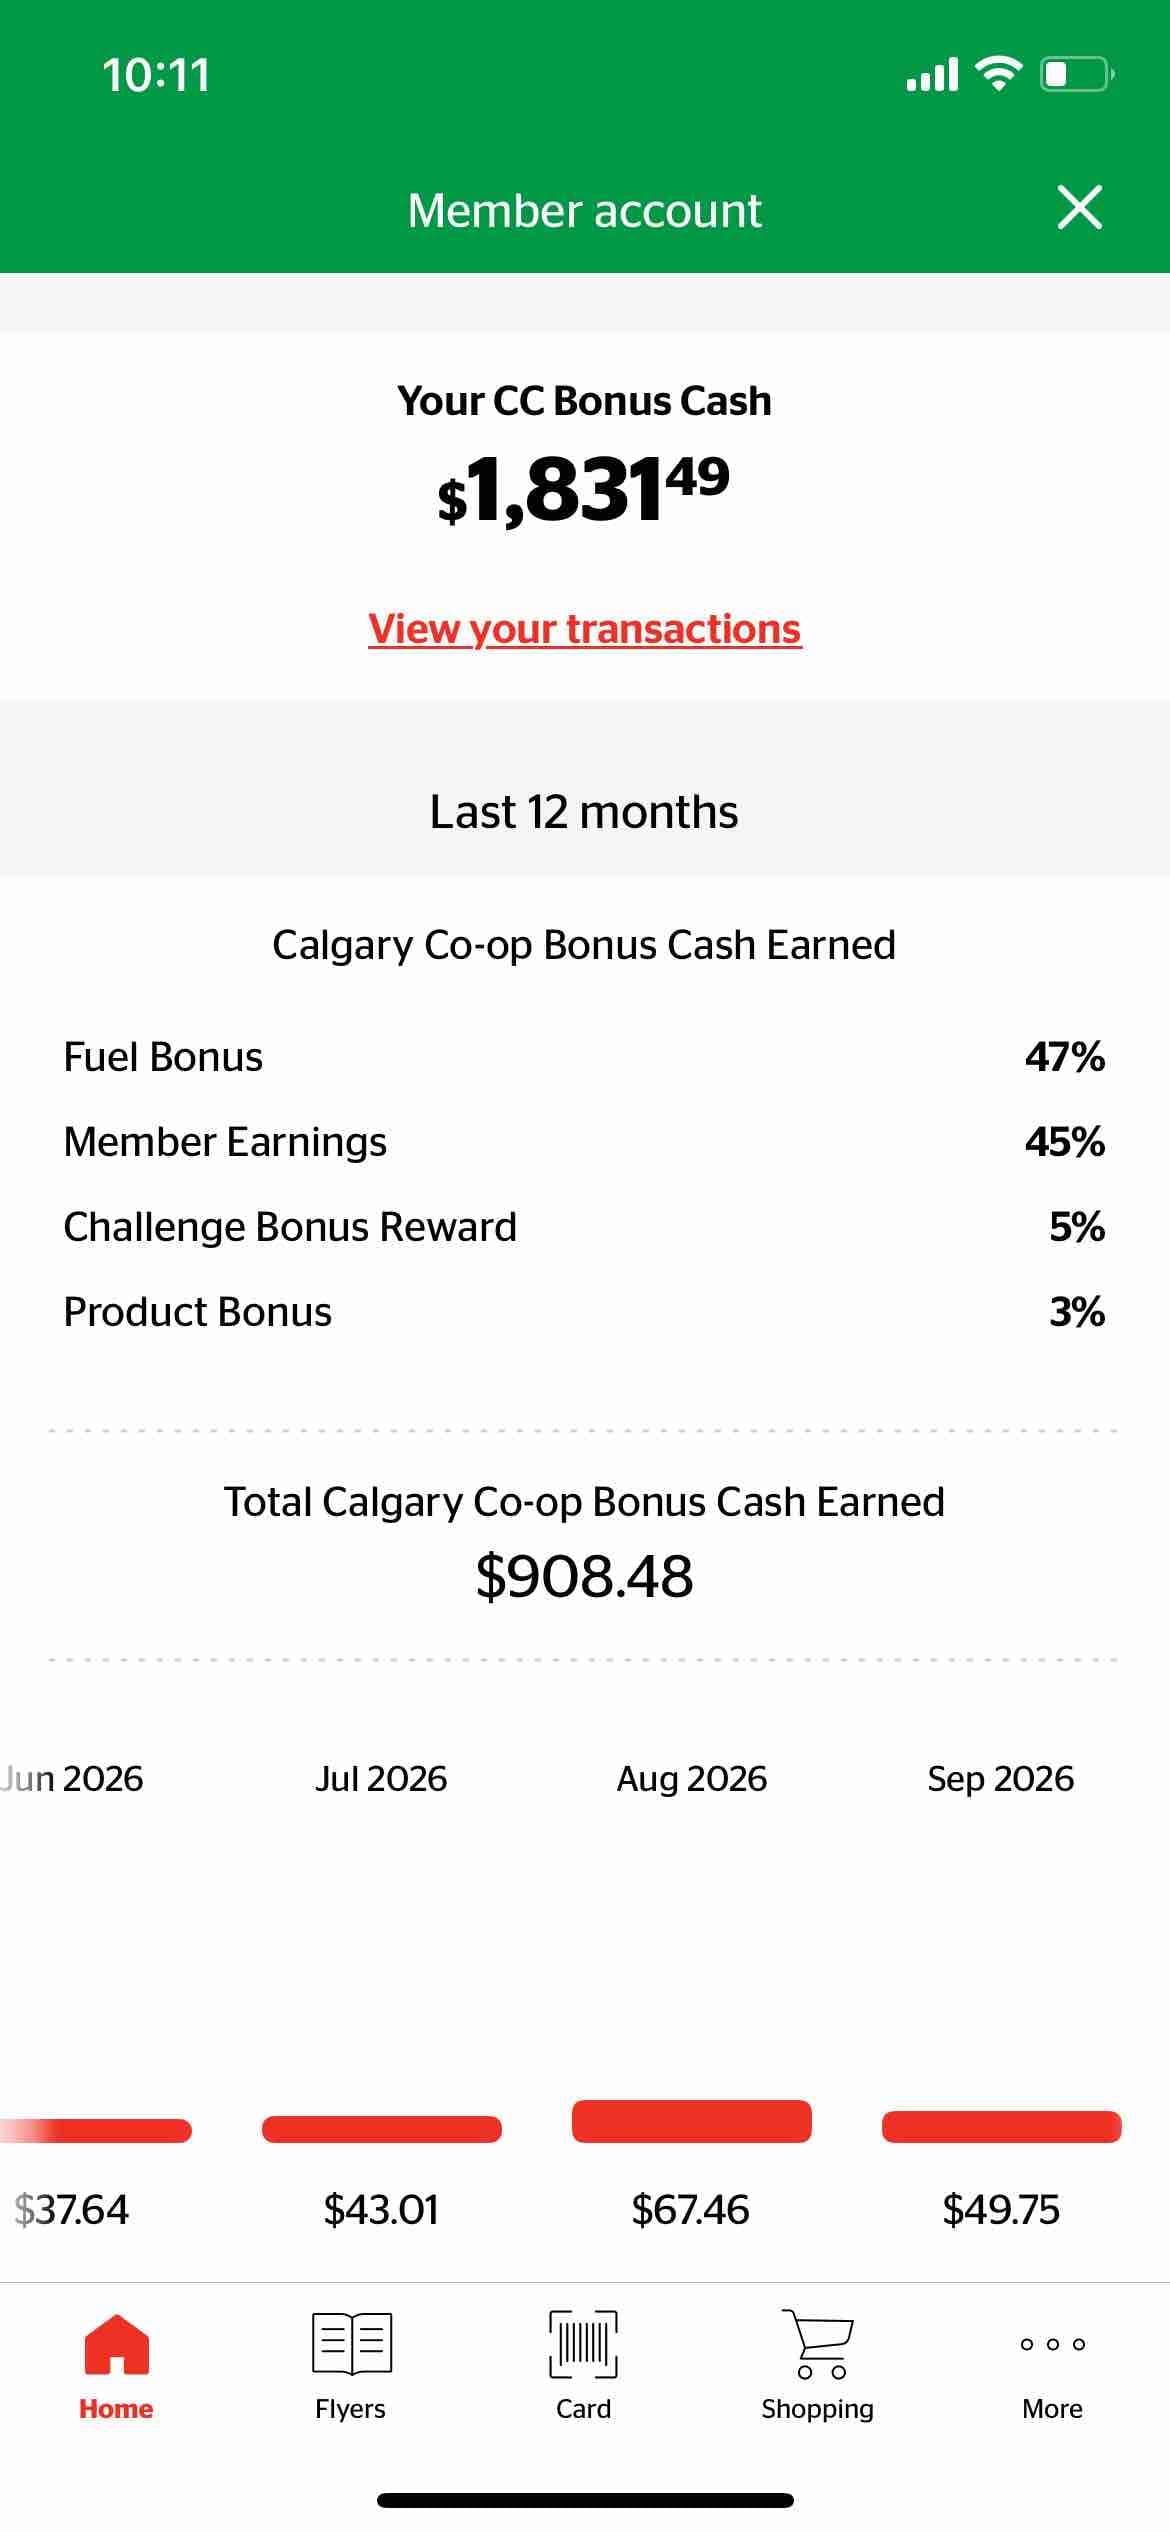
Last week my company issued fuel card for my work truck was not working properly. Called my boss and let them know and he was in a panic on how to get fuel for me without impacting production. My response was don’t worry about a thing. I’ll put it in my card just reimburse be on my next pay. His response was wow you’ll actually foot the bill? I was like damn right! I recieved $21.06 from my credit card NEO World Elite Mastercard $6.38 in cash back from Co-op 4 cents per litre plus another $6.38 4 cents per litre that will be added to my equity total that will be paid in January! Total of 8 cents per litre. Plus $5 cash back challenge rewards for purchase of more than 115l. So grand total of $32.44 cash in hand on money that I’m getting reimbursed for on my next pay check tax free. $410 fuel purchase! Which of course will all be invested! read more
🔒Ex-date Tuesday💰Paydate Wednesday $WPAY is now $TOPW since couple of months $TOPW$0.238142⬆️ Last week : $TOPW$0.230055⬆️ 2 weeks ago : $TOPW$0.219827⬇️ 3 weeks ago : $TOPW$0.249134⬆️ 4 weeks ago : $TOPW$0.187370⬇️ 5 weeks ago : $TOPW$0.203850⬇️ 6 weeks ago : $TOPW$0.293120⬆️ 7 weeks ago : $TOPW$0.228021⬆️ 8 weeks ago : $TOPW$0.207141⬇️ 9 weeks ago : $TOPW$0.231020⬇️ 10 weeks ago : $TOPW$0.309598⬆️ read more
For people who are interested in income investing, Steven Bavaria is one of the longer-running public voices in the space. He has been writing about income investing on Seeking Alpha for years and is the author of The Income Factory. This is from a recent interview he did where he explained the basic idea behind the strategy. The Income Factory theory, if you want to call it that, is actually pretty simple. Total return can be achieved just as much through cash income as it can through capital gains. If an investment earns a 10% total return, theoretically that return could come from a 10% yield and 0% capital appreciation, a 0% yield and 10% capital appreciation. When he was asked, “How do you measure the results of an Income Factory?” he answered the same way you should measure almost any investment strategy: total return. Total return is the most important statistic when you are trying to determine how the investment itself has actually performed. A fund can distribute 14% or 15% a year, but that does not necessarily mean the investor earned 14% or 15%. Bavaria explained it this way: “So, not to make it too complicated, but the key thing is if you collect 14% or 15%, which is great, don't assume that you're going to keep it all. You know, make sure you check the total return of that fund. And just look at it over time to make sure that the total return, what you've got after the erosion of price, is sufficient.” “And you'd say to yourself, okay, I collected 12%, but I gave back 4% in the erosion of the price or the net asset value, so my net return is 8%. Now, that would be step one. And you might then say, well, 8%, that's still a decent total return. If my overall portfolio over many years earned 8% to 9%, that'd be fine. But you'd have to then make sure that if you got 12% but really were only earning 8% because four of it was being eroded away in the price, in the NAV, you'd want to make sure that at the very least you reinvested 4% of that 12%. And that would only just keep you even.” You can watch the whole interview below The Income Factory | Generating Monthly Cash Flow With 9%+ Yields (Steven Bavaria) https://www.youtube.com/watch?v=-cC91dSmiJQ read more