Semis on green days can often be found at the top of a watchlist, but on red days like today at the bottom. Some advocate building portfolios targeting low volatility and Beta, but I do the opposite. When you are a long term buy and hold investor, optimizing for short term volatility makes no sense in my opinion. What I prefer to target is companies and sectors that have the greatest potential for large revenue and earnings growth. The world needs far more compute, memory, and semi products in my opinion going into the future, so I remain enthusiastic and committed to the sector despite the volatility. https://youtu.be/HncnpjM0XuY?si=tD0SS-eTE_tbABhkread more
eMarketer projects Meta to surpass Google for the first time ever in net Ad Revenue... 2026 Worldwide Ad Wallet-Share: - Google Ecosystem: 24% - Facebook: 16% - Instagram: 10.5% - YouTube: 2.4% (Source: eMarketer Forcast) $GOOGL$GOOG$META$METAread more
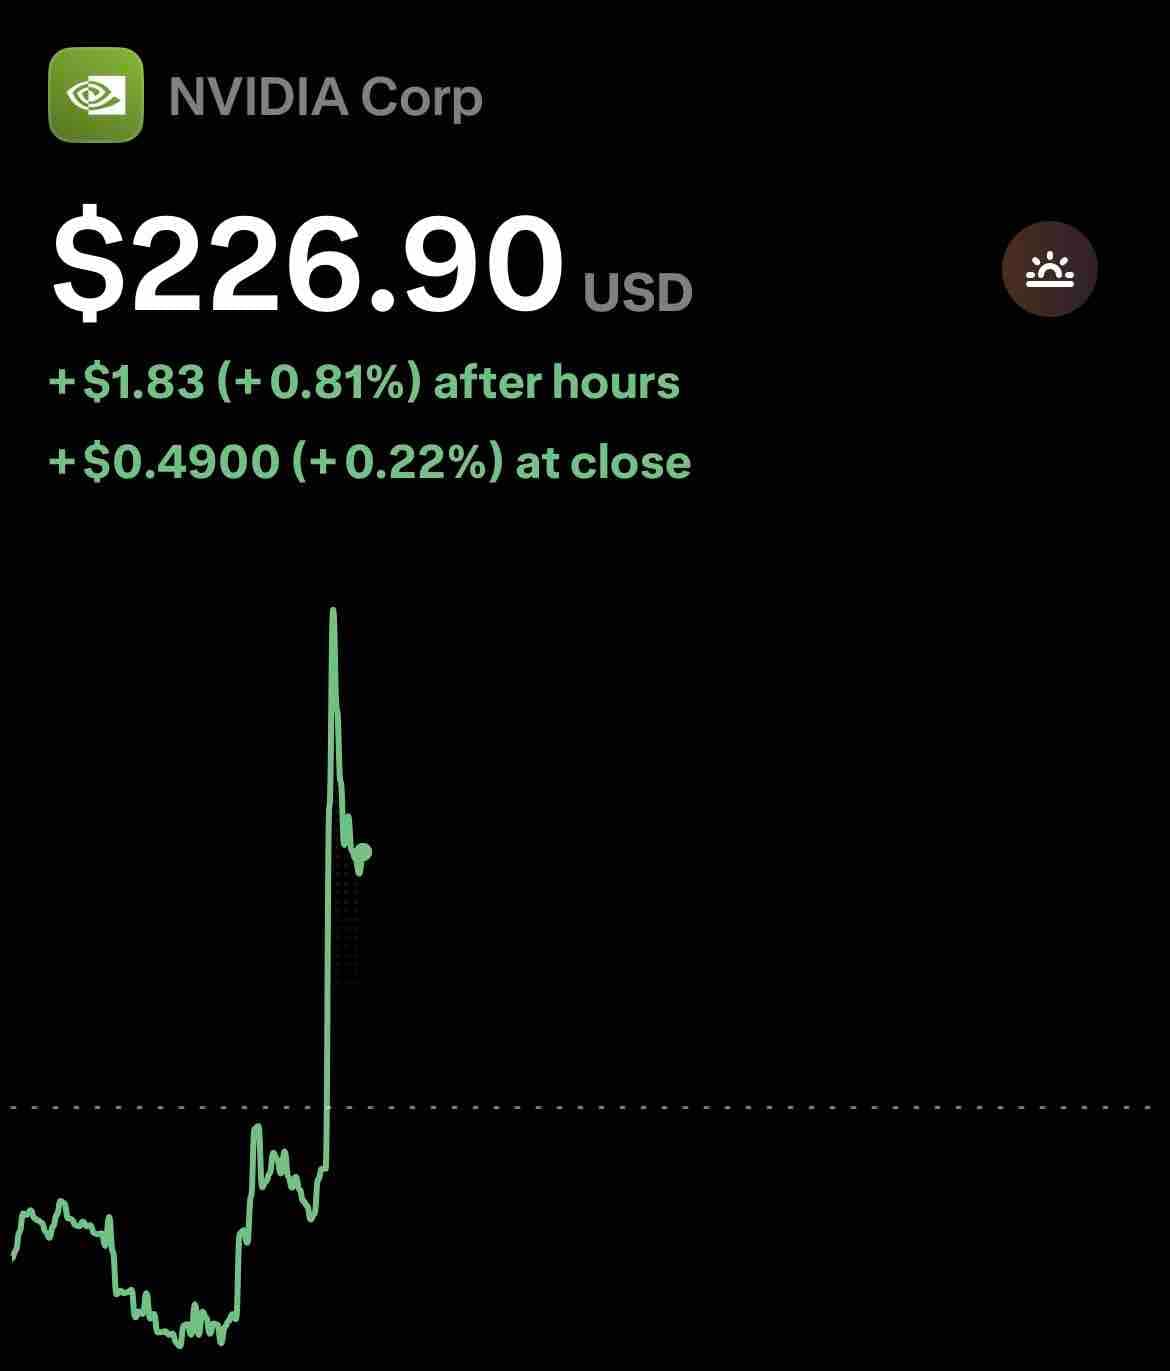
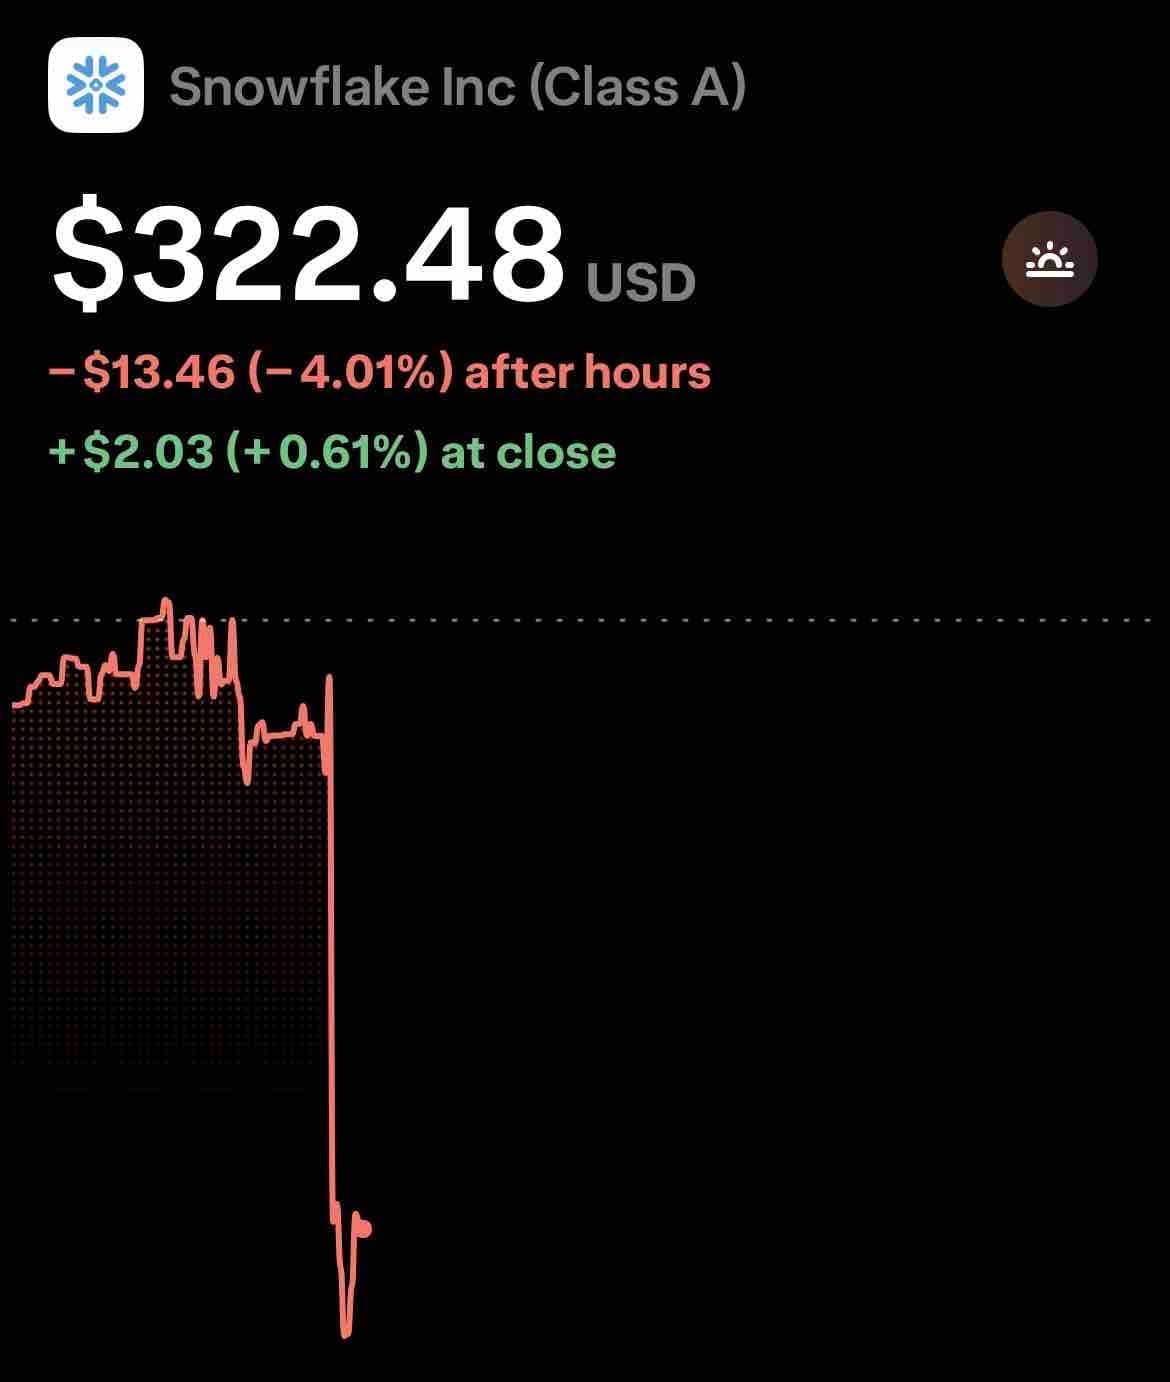
$NVDA just announced an increase to its share buyback authorization, bringing it to $150B. Meanwhile, $SNOW announced plans to raise $3.5B through convertible notes due in 2027 and is down about 4% premarket. Two big announcements to watch today. Which stock are you watching closer?
Trump is set to make an announcement today at 2:00 p.m. ET, and apparently nobody knows what he is going to announce. So naturally, the market gets to spend the morning playing everybody’s favorite game: Guess What Trump Is Going to Say. Is it AI related after his dinner with Anthropic CEO Dario Amodei? Is it connected to the recent visit from Chinese President Xi Jinping? Is it something involving Iran? World trade they just had that big UN conference? As a Canadian, maybe they are going to announce something involving Canada although I wouldn’t bet on that. Something with tariffs? They have already announced another reduction in Chinese tariffs. Maybe he is going to talk about energy prices? Or is he going to walk out at 2:00 and announce something completely random that nobody saw coming? Allegedly nobody knows, but whatever he says could send the market higher or lower in a matter of seconds. You can analyze earnings, study the balance sheets, calculate valuations, interest rates and expected returns. But now we need a new spot on the spreadsheet for U.S. Presidential Announcements, a line item I never expected to have to add but one that lately seems almost more relevant than some of the others. And that whole “nobody knows” Well, if you are paying the $100,000 early access fee, maybe you might just get a glimpse before the move. Are we going to see some unusual activity in the market before the announcement? What a time to be in the stock market.
I’m rotating $1,600 of $HIMS into $UBER today and here’s why👇 My base case for Uber gives me a 20% CAGR until 2031 assuming 12% FcF / Share CAGR & an exit FcF multiple of 20x. My average cost in HIMS was $29.10 so selling it at prettt much the same cost I bought in at. This gets me down to 15 positions in my portfolio getting me closer to my goal of 10-12 and hims is the stock I’m the least sure about for the future making it the obvious choice to be cut. Uber on the other hand has seen millions of insider buying with the CEO buying $10 million and the COO buying $5 million along with Nancy Pelosi and other politicians buying. Uber has the bear case completely priced in already with robotaxis and waymo scaring investors off of Uber. But at 17x forward earnings I believe uber is an absolute steal here and I will continue to buy. read more
Bull: If Now Assist ACV keeps compounding past the newly-raised $1.5B 2026 target and enterprise AI adoption broadens, NOW could keep growing revenue in the low-to-mid 20s% for years, with margins eventually catching up as AI infrastructure spend normalizes and the forward multiple has room to re-rate back toward its historical 45–60x range if that plays out. Bear: AI infrastructure spend could keep pressuring margins longer than expected (net income has been essentially flat for two straight reporting periods), and Salesforce/Workday could compete more aggressively on price as AI commoditizes core workflow tooling - at a premium-to-peers valuation, there's less room for error than a truly cheap stock. $NOW
Shopify is expensive but justified. This is the 'pay up for a durable moat and proven growth' bucket. The Meta deal is a genuine moat-widening catalyst, and Bernstein's fresh initiation reflects the market correctly re-pricing that. $SHOP
NVIDIA $NVDA Announces a $150 Billion Share Repurchase Authorization Increase Good announcement with the Nazzy down almost -1% pre-market. On the other hand, $SNOW is raising $3.5B through 0% convertible notes due 2027. -4% pre-market.
Something you don’t see often: Mark Zuckerberg just announced MongoDB $MDB CEO Chirantan Desai is leaving MongoDB to join $META as the head of its Meta Enterprise Platform Unit That’s business for ya! $MDB fell off a cliff pre-market down -16%. Call an ambulance..
SpaceX has a whopping $100B in cash & equivalents at the end of Q2. Revenue is expected to 20x (!) over the course of 4-5 years going from $7B to $140B in 2030. $ASTS gotta get those launches underway! Positive for the entire sector proving monetization and sheer scale. $SPCX$RKLB
Last Wednesday retail investors sold $300 million of ETFs in a single day, the largest daily sale on record. That beats the $260 million set during the March 2020 pandemic crash. The selling was concentrated. SOXX, the semiconductor ETF, saw $270 million of retail outflows in one day, its largest daily retail withdrawal in at least a year, and $695 million across the week. SOXL, the 3x leveraged semi fund, lost $1.2 billion. Retail is locking in gains in chips. Nvidia disagreed This morning Nvidia's board added $150 billion to its buyback authorization. Total now stands at $235 billion, to be executed through fiscal 2028. For scale, that authorization alone is larger than the entire market cap of all but roughly thirty US companies. Retail sold the sector at a record pace. The sector's biggest company authorized the largest repurchase programme in corporate history. Somebody is wrong. The bigger story from the weekend The peace trade died on Saturday On 25 September Iran's foreign minister put a seven-day plan to US mediators, reopen the Strait of Hormuz and restart nuclear talks, in exchange for lifting the naval blockade, waiving sanctions on Iranian oil, and a ceasefire across all theatres including Lebanon. Trump rejected it the next day. His words: "I'm rejecting their deal. They want to make a deal where they open the strait immediately because they are losing so badly." He added that it was what the US "would have maybe agreed to a year ago." The Wall Street Journal reported he expects bombing to resume after the 3 November midterms. Asked directly by Fox whether strikes before the midterms were still on the table, he said "it's possible, but I just don't want to say that." That is the single most important thing that happened since Friday, and it repriced four asset classes at once. Oil reversed hard WTI is up more than 4% this morning to around $96.44, Brent to $108.42. On Friday WTI closed at $92.89 and Brent at $105.40, both falling on ceasefire optimism. Worth noting what the US has actually achieved militarily: roughly 40 million barrels escorted through Hormuz in 48 hours, matching pre-war throughput, with 122 vessels redirected. Washington now believes it holds the waterway. That is precisely why the deal was refused. Bonds are at generational highs Ten year at 5.235% this morning, up nearly five basis points. Thirty year at 5.538%. Two year at 4.916%. Friday's close of 5.225% on the ten year was the highest since 2007. The thirty year is at levels last seen in 2004. Four things are pushing at once: diesel around $6.50 a gallon and petrol near $4.50 feeding inflation, traders pricing hikes at the next two meetings, a deteriorating federal fiscal picture, and AI capex competing for the same pool of capital. JPMorgan's line was that ten year yields could reach roughly 5% before equity multiples start to compress. We are through it. Gold and silver are breaking Gold down about 3% this morning to roughly $4,153. Silver down nearly 5% to $61.09. On Friday both were up. Gold closed +0.91% at $4,337 and silver +1.90% at $65.22. So this is a two-session reversal, not a trend. Gold's record was $5,419.83 on 28 January. It is now down roughly 23% from that. But look at who is buying Goldman estimates central banks bought 44 tonnes of gold in July, 158% above the pre-2022 average of 17 tonnes. The three month average sits near 91 tonnes, close to its highest since mid-2025. Officially reported purchases were 23 tonnes. That is a 21 tonne gap between what central banks say they bought and what the data suggests they actually bought. Price falling, sovereign accumulation rising, and the buyers not putting their names to it. That is a more interesting chart than the one showing the selloff. What this week looks like Tuesday: September consumer confidence and August JOLTS. Wednesday: August PCE, the Fed's preferred inflation measure, plus Q2 GDP. Thursday: September ISM manufacturing. Friday: the September jobs report. On top of that, somewhere between 19 and 22 separate Fed speaker events, with six on Thursday alone. That is the entire macro picture compressed into four days, into a bond market already at 2007 yields, with oil back above $108 because a ceasefire failed. Where I come out Last week the S&P still gained 0.63% and the Nasdaq 1.21% while the ten year broke to a nineteen year high. Equities have spent a month refusing to care about rates. Wednesday's PCE print is where that gets tested properly, because it is the number that decides whether "hikes at the next two meetings" becomes "hikes at the next three." And the Nvidia buyback is worth holding onto as a question rather than an answer. A $235 billion authorization is either the most confident capital allocation decision of this cycle, or it is what a company does when it has more cash than ideas. We find out which over the next two years, not this week. Futures are pointing lower into all of it. Dow off around 250, Nasdaq down about 1%. read more
$MU is one of my key names heading into this week. AI-driven memory demand remains strong, and Micron’s fundamentals continue to support the bullish thesis. Earnings are Wednesday after the close. I’m watching the price action closely — the reaction to guidance will be just as important as the numbers themselves. $MU 📊
Friday: $DIA +0.93%, $SPY +0.51%, $QQQ +0.48%. Week: $SPY +1.2%, $QQQ +2.1%, Dow snapped a 3-week losing streak. 10-yr yield closed at 5.184%, highest close since 2007. This morning: Trump reportedly rejected Iran's Hormuz proposal. Oil jumping (WTI +4%), gold down 3%, futures turning lower — $QQQ -1.0%. Big week: Micron earnings Tuesday, Core PCE + GDP Wednesday, jobs report Friday. Margin still coasting down toward the low 30s. Full breakdown — link in bio. Not financial advice — simply my journey in margin.